


Carbon Accounting Software Market Size & Forecast 2026–2035
Market Overview
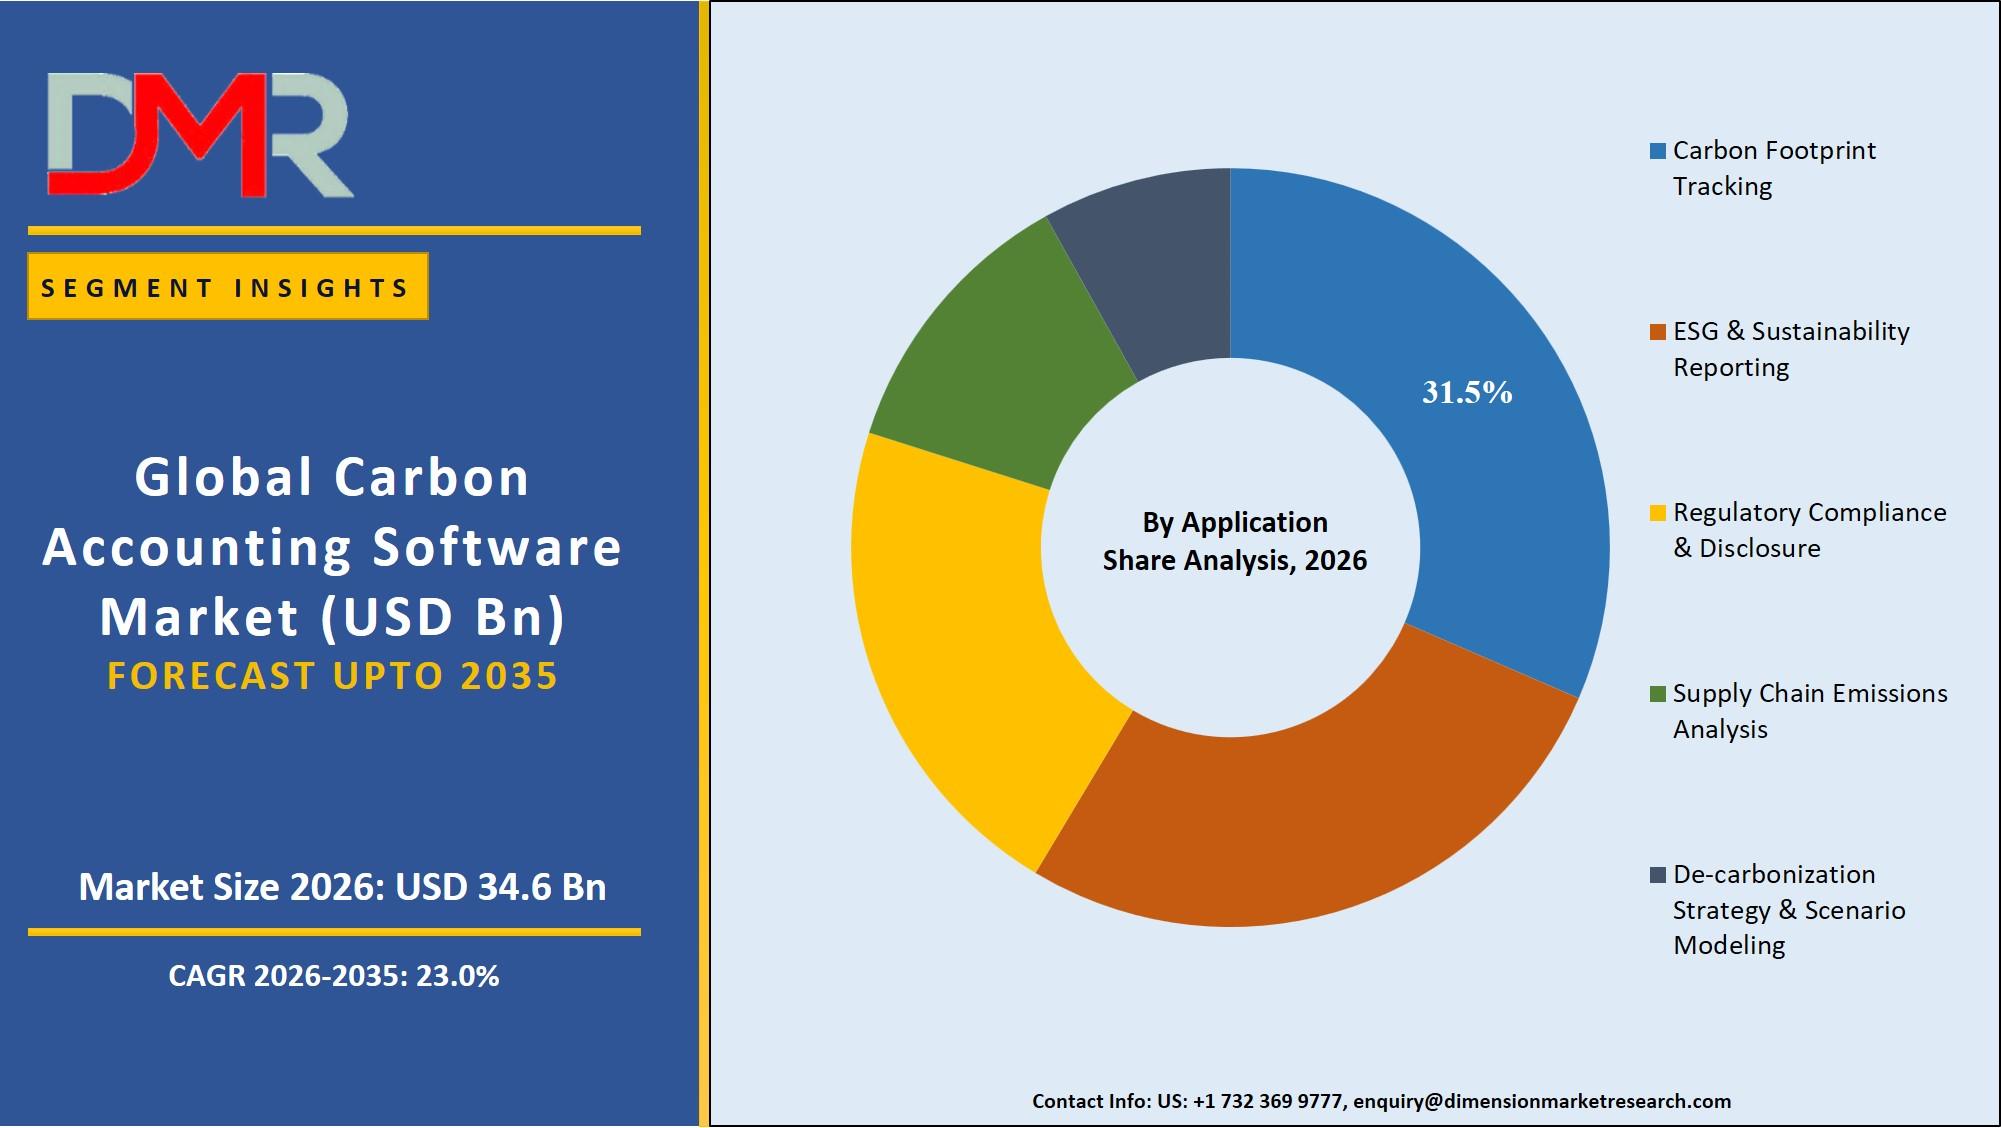
According to Dimension Market Research, the Global Carbon Accounting Software Market is expected to reach a value of USD 34.6 billion in 2026, and it is further anticipated to reach USD 223.4 billion by 2035, growing at a CAGR of 23.0% during the forecast period. The market is witnessing explosive growth due to increasing regulatory pressure on emissions disclosure, aggressive corporate net-zero commitments, rising demand for accurate Scope 1, 2, and 3 emissions tracking, and the growing need for audit-ready sustainability reporting across industries.
Carbon accounting software refers to specialized digital platforms that enable organizations to measure, monitor, report, and reduce greenhouse gas (GHG) emissions across their operations and value chains. These solutions automate the collection of emissions data from multiple sources, apply standardized calculation methodologies, and generate reports aligned with frameworks such as the GHG Protocol, CDP, TCFD, and emerging regulatory standards.
The global carbon accounting software market is experiencing rapid expansion as enterprises face mounting pressure from regulators, investors, and consumers to demonstrate credible climate action. Organizations are moving away from manual spreadsheet-based approaches toward integrated software platforms that provide real-time visibility, audit trails, and analytics-driven insights for decarbonization planning.
The integration of AI, machine learning, and advanced analytics into carbon accounting platforms is further transforming the market, enabling predictive emissions modeling, anomaly detection, and automated data validation. The growing adoption of cloud-based solutions is also accelerating deployment, scalability, and collaboration across distributed operations and supply chains.
Definition and Market Significance
Carbon accounting software is a specialized digital platform designed to help organizations quantify, track, and report greenhouse gas emissions across their operations, supply chains, and value chains. These solutions support measurement of Scope 1 (direct emissions), Scope 2 (indirect energy emissions), and Scope 3 (value chain emissions), applying standardized methodologies and regulatory frameworks.
The importance of carbon accounting software lies in its critical role in enabling credible climate action, regulatory compliance, and stakeholder transparency. As governments and regulators worldwide introduce mandatory emissions disclosure requirements, organizations require robust, auditable systems to accurately measure and report their carbon footprint.
Carbon accounting software also supports broader sustainability objectives by enabling data-driven decarbonization strategies, identifying emissions hotspots, tracking progress against net-zero targets, and facilitating integration with ESG reporting and enterprise risk management systems.
Request a Complimentary PDF Sample
https://dimensionmarketresearch.com/request-sample/carbon-accounting-software-market/
Market Drivers
A major factor driving the Carbon Accounting Software Market is the increasing regulatory pressure on emissions disclosure. Governments worldwide are introducing mandatory climate reporting requirements, including the EU Corporate Sustainability Reporting Directive (CSRD), SEC climate disclosure rules in the United States, and similar frameworks in Asia Pacific, compelling organizations to invest in robust carbon accounting systems.
Aggressive corporate net-zero commitments are another key driver supporting market expansion. Thousands of companies have pledged to achieve net-zero emissions by 2050 or earlier, requiring accurate baseline measurement, ongoing tracking, and transparent reporting of progress, which drives demand for sophisticated carbon accounting platforms.
The growing demand for Scope 3 emissions tracking is also contributing to market growth, as organizations recognize that value chain emissions often represent the largest portion of their carbon footprint and require advanced data collection and collaboration capabilities across suppliers and partners.
Market Trends
The integration of AI and advanced analytics into carbon accounting platforms is emerging as an important trend in the market. AI-powered tools enable predictive emissions modeling, anomaly detection, automated data validation, and intelligent recommendations for emissions reduction, enhancing the accuracy and actionability of carbon data.
Another significant trend is the convergence of carbon accounting with broader ESG and sustainability management platforms. Organizations are increasingly seeking integrated solutions that combine carbon accounting, ESG reporting, energy management, and risk assessment into unified platforms, reducing complexity and improving data consistency.
The growing adoption of cloud-based and API-driven carbon accounting solutions is also transforming the market, enabling real-time data integration with ERP, supply chain, and IoT systems, and facilitating collaboration across distributed operations and value chain partners.
Market Restraints
Despite its strong growth potential, the Carbon Accounting Software Market faces certain limitations. Data quality and availability challenges pose significant restraints, as organizations struggle to collect accurate emissions data from diverse sources, including suppliers, logistics providers, and third-party operations, particularly for Scope 3 emissions.
High implementation costs and complexity are another significant restraint. Deploying comprehensive carbon accounting platforms requires investment in software, integration, training, and change management, which can be prohibitive for smaller organizations with limited budgets and technical resources.
In addition, the lack of standardization across carbon accounting methodologies and reporting frameworks can create confusion and increase compliance complexity, particularly for multinational organizations operating across multiple jurisdictions.
Market Opportunities
The expansion of carbon accounting software into supply chain and Scope 3 emissions management presents significant growth opportunities. As organizations increasingly recognize the importance of value chain emissions, demand for platforms that enable supplier engagement, data collection, and collaborative decarbonization is expected to grow rapidly.
The integration of carbon accounting with carbon credit markets and offset management is another promising opportunity. Organizations seeking to neutralize residual emissions require platforms that can track carbon credits, verify offset quality, and integrate offset management with emissions accounting.
Furthermore, the growth of mandatory climate disclosure requirements in emerging markets and the increasing adoption of carbon pricing mechanisms are expected to open new opportunities for carbon accounting software providers globally.
Segmentation
The Carbon Accounting Software Market is categorized based on component, deployment mode, organization size, application, and end-user industry.
By component, software platforms are expected to hold the largest share, driven by demand for automated emissions data collection, calculation, and reporting capabilities. Services, including consulting, implementation, and managed services, are growing rapidly as organizations seek expert support for complex carbon accounting initiatives.
By deployment mode, cloud-based solutions are expected to dominate, driven by scalability, accessibility, integration capabilities, and lower upfront costs. On-premises deployment remains relevant for organizations with strict data sovereignty and security requirements.
By organization size, large enterprises are expected to lead, driven by complex regulatory requirements, global operations, and greater resources for sustainability initiatives. SMEs are increasingly adopting cloud-based carbon accounting solutions as regulatory requirements expand.
By application, emissions measurement and reporting is expected to hold the largest share, followed by decarbonization planning, supply chain emissions management, and carbon credit management.
By end-user industry, manufacturing, energy and utilities, BFSI, retail, technology, and transportation are key segments, with manufacturing and energy leading due to their high emissions profiles and regulatory exposure.
Regional Analysis
North America is poised to dominate the global carbon accounting software market as it is projected to hold 37.8% of the market share by the end of 2026. The United States, which dominates North America, has the highest share in the carbon accounting software market because of the unmatched concentration of climate tech innovation hubs and the aggressive net-zero agendas of the Fortune 500 companies. The area has an established ecosystem of global system integrators, boutique climate consultancies, and rich pool of talent in carbon accounting and data science. Enterprise investment in artificial intelligence, advanced analytics, and the overall retirement of manual data collection methods contribute to the continued demand for emission management software and the continuous optimization of energy efficiency. Moreover, an optimistic venture capital climate persistently finances upcoming carbon accounting startups that need to achieve expeditious development and data security compliance.
Europe holds a substantial share of the carbon accounting software market, driven by the EU Corporate Sustainability Reporting Directive (CSRD), the EU Taxonomy, and other stringent climate disclosure requirements. Countries such as Germany, France, the Netherlands, and the Nordics are leading adopters, with strong demand from manufacturing, energy, and financial services sectors.
Asia Pacific is projected to be the fastest-growing region, driven by rapid industrialization, expanding regulatory frameworks, and increasing corporate commitments to sustainability in countries such as China, Japan, South Korea, India, and Australia. Government initiatives promoting carbon neutrality and green finance are further accelerating market growth.
Latin America and the Middle East & Africa are gradually adopting carbon accounting software as sustainability awareness grows and regulatory frameworks evolve, with Brazil, Mexico, the UAE, and Saudi Arabia emerging as key markets.
Competitive Landscape
The carbon accounting software market is highly competitive, with a mix of specialized climate tech companies, enterprise software vendors, and professional services firms competing across functionality, data integration capabilities, regulatory coverage, and industry expertise. Companies are investing in AI-powered analytics, expanded emissions factor databases, and integration with enterprise systems to strengthen their offerings.
Prominent players include Salesforce (Net Zero Cloud), SAP, IBM, Microsoft, Persefoni, Watershed, Sphera, Carbon Trust, Plan A, Sweep, Greenly, Normative, and various specialized climate tech startups. Recent developments include strategic partnerships, new regulatory reporting modules, and acquisitions aimed at expanding capabilities and geographic reach.
Technological Advancements
Rapid advancements in AI, machine learning, and data integration technologies are transforming the carbon accounting software market. AI-powered platforms enable automated emissions data collection, validation, and anomaly detection, while advanced analytics support predictive modeling and decarbonization planning.
The integration of carbon accounting software with ERP, supply chain, energy management, and IoT systems is also playing a significant role, enabling real-time emissions tracking, automated reporting, and seamless data flow across organizational boundaries.
Consumer Adoption Patterns
Organizations across manufacturing, energy, financial services, retail, technology, and transportation sectors are increasingly adopting carbon accounting software to meet regulatory requirements, track net-zero progress, and demonstrate climate leadership. The growing availability of cloud-based and modular solutions is making adoption more accessible to organizations of all sizes.
Regulatory Environment
Regulatory frameworks across different regions, including the EU CSRD, SEC climate disclosure rules, TCFD recommendations, and emerging national carbon pricing mechanisms, significantly influence the carbon accounting software market. Compliance with these regulations drives demand for accurate, auditable, and standardized emissions reporting capabilities.
Market Challenges
The carbon accounting software market faces challenges related to data quality and availability, particularly for Scope 3 emissions, high implementation costs, lack of standardization across methodologies, and the need for skilled professionals to manage complex sustainability reporting requirements.
Future Outlook
The future of the Carbon Accounting Software Market remains exceptionally promising as regulatory pressure intensifies and corporate net-zero commitments expand. Increasing adoption of AI-powered platforms, growth of Scope 3 emissions management, integration with carbon credit markets, and expansion into emerging markets are expected to drive strong market growth during the forecast period, with the market projected to reach USD 223.4 billion by 2035 at a CAGR of 23.0%.
FAQs
What is the expected size of the Carbon Accounting Software Market in 2026?
The market is expected to reach USD 34.6 billion in 2026.
What is the projected market value by 2035?
The market is forecast to reach USD 223.4 billion by 2035.
What is the CAGR of the Carbon Accounting Software Market?
The market is expected to grow at a CAGR of 23.0% during 2026–2035.
Which component segment dominates the market?
Software platforms are expected to hold the largest share.
Which region leads the global carbon accounting software market?
North America is projected to hold 37.8% of the market share in 2026.
Summary of Key Insights
The global Carbon Accounting Software Market is expected to grow from USD 34.6 billion in 2026 to USD 223.4 billion by 2035, recording a CAGR of 23.0% during the forecast period. Software platforms lead the component segment, while cloud-based deployment dominates. Large enterprises lead by organization size, emissions measurement and reporting leads applications, and manufacturing and energy lead end-user industries. North America holds the largest regional share with 37.8% of global revenue in 2026, while Asia Pacific is projected as the fastest-growing region.
Purchase the Full Report
https://dimensionmarketresearch.com/checkout/carbon-accounting-software-market/
